A sale falls through, a tenancy ends before the new flat is ready, or an office lease starts before the replacement space can accept furniture. In London, that can leave a household’s belongings moving from a terrace in Clapham to temporary storage in Bermondsey, with no clear answer about which policy protects the goods at each stage. The removal van, the warehouse, the storage container and the delivery crew may all sit under different contractual responsibilities.
Storage insurance coverage only works when those handover points are understood. The relevant question isn’t whether the goods are “fully insured.” It’s which policy responds, at what moment, for which cause of loss, and up to what declared value. This guide maps cover onto the phases of a London move, from uplift through storage to final delivery.
Why storage cover matters on a London move
A Clapham family can have everything packed and labelled when a property chain collapses on completion day. Their three-bedroom terrace is no longer available, the onward property can’t receive furniture, and several weeks of storage in Bermondsey becomes the only workable option. The risk starts before the goods reach the warehouse.
At the front door, a crew deals with a parking suspension, narrow access and stairwells or lifts governed by building rules. An Islington mansion block may restrict goods-lift use to certain hours, while a congested route through Camden can add handling time and increase the number of movements between the property and the van. None of that tells the customer, on its own, which insurance clause applies.
The risk begins at uplift
Goods can be damaged while furniture is dismantled, packed, carried through a communal hallway, loaded into the vehicle and secured for travel. A standard home contents policy may not extend to goods held by a third party or to accidental damage during a professional move. Even where some off-site protection exists, its exclusions, limits and treatment of transit may differ from a removals company’s policy.
The removals contract should identify the point at which the crew accepts custody. The survey, inventory and condition notes matter because a later claim may depend on whether a mark existed before uplift or appeared during handling.
Practical rule: “fully insured” isn’t a useful answer unless the contract names the insured goods, the covered risks, the value basis and the custody period.
Storage creates a second exposure
Once goods enter storage, fire, theft, flood, escape of water and impact become warehouse risks rather than ordinary household risks. There’s generally no legal requirement to buy a storage provider’s own policy, but a provider can require proof of equivalent cover under the rental contract, and customers can usually arrange suitable cover independently, provided the policy meets the operator’s conditions.
The Self Storage Association UK’s 2026 industry report shows the scale of the sector this sits within: annual turnover of around £1.3 billion, overall occupancy of 74.5% and mature-store occupancy of 79.6%. Coverage arrangements vary widely across that many customers, which is exactly why the contract wording matters more than assumptions based on the existence of a home policy.
Delivery is another handover
The warehouse door closing doesn’t end the risk. Cover may change again when a container is opened, goods are transferred to a delivery vehicle, and furniture is carried into a property. A delivery to a flat in Wandsworth can involve a controlled parking zone, a long carry from the vehicle and a lift booking that expires before the last item arrives.
The practical questions are straightforward. When does storage cover start? Does it include loading and unloading? Does transit cover apply again for redelivery? What happens if a customer arranges a separate man and van service for the final leg? Those answers belong in the documents before the goods leave the original address.
How goods-in-transit, transit, and storage cover differ
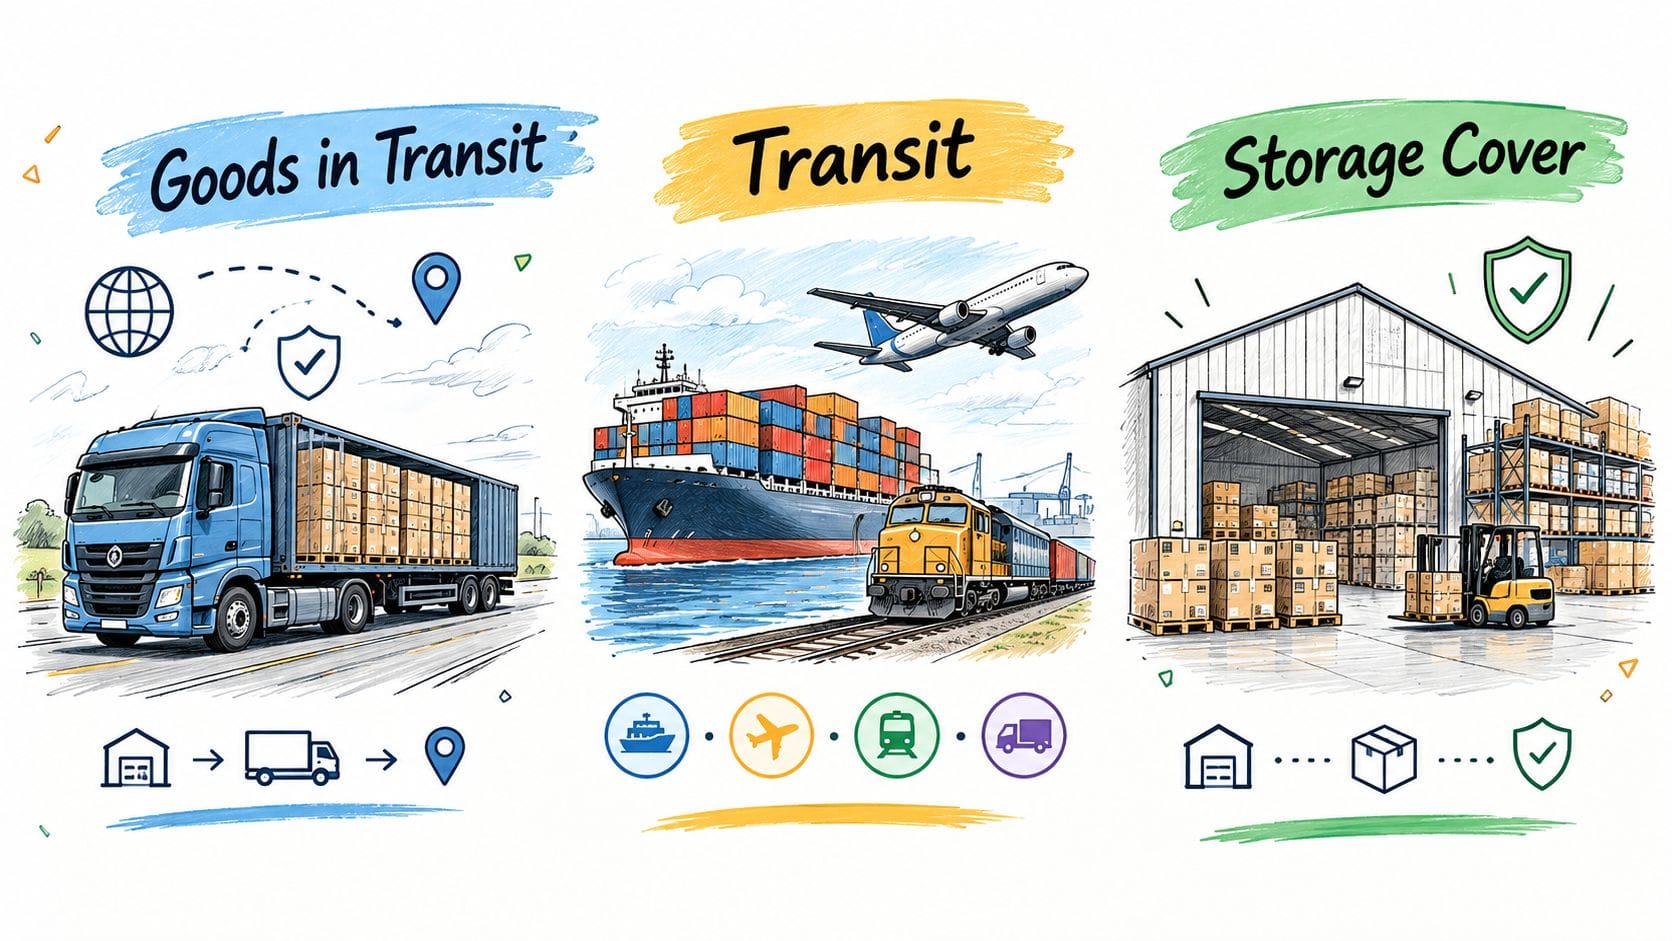
A London removals arrangement creates distinct risk windows, even when one company coordinates the whole move. Goods-in-transit cover normally protects possessions while the removal vehicle travels between addresses. The exact wording controls the start and finish, but the usual boundary runs from loading at the origin to the first unloading point. Our goods-in-transit insurance guide sets out what that cover typically includes and how it’s priced.
“Transit cover” is sometimes used as a broader removals term for the same journey, including incidental handling connected with the move. It shouldn’t be treated as proof that warehouse storage is included. A customer needs the schedule and wording, not the label used in a quotation.
A Fulham move shows the boundary
Consider furniture collected from a Fulham flat and placed into a Chelsea storage unit. A cracked dining table discovered after the vehicle journey is normally investigated under the removals or transit arrangement, because the damage occurred during the transport phase. Water damage found inside a sealed unit is a storage claim, subject to the storage policy’s covered perils, exclusions and declared value.
The handover point may sit at the warehouse threshold, when goods are placed into the storage container, and the container is sealed. Some policies describe cover as beginning when goods are placed in the unit and continuing until final removal, provided the required premium remains paid. Others tie protection to a specified storage address or impose conditions about access.
Long-term storage is therefore not an automatic extension of transit cover. The operator, the removals company and the customer should record the facility address, the sealed-container reference, the inventory and the date responsibility changes. Without those records, a claim can be sent to the wrong insurer or assessed under the wrong policy. Our long-term storage guide covers how those arrangements are typically structured.
What storage insurance typically covers and excludes
UK storage insurance commonly uses named-perils wording. That means the policy responds to listed causes of loss, not to every form of damage that happens while goods are in a unit. Typical covered events can include fire, flood, theft following forcible and violent entry, storm, escape of water, impact and vandalism, subject to the individual policy.
| Cover element | Typical treatment |
|---|---|
| Fire and flood | Commonly included as named perils, subject to wording and conditions |
| Theft | Often requires forcible and violent entry |
| Storm and impact | Usually covered when the event meets the policy definition |
| Escape of water | May be included, but damp and gradual moisture damage can remain excluded |
| Mould, mildew and vermin | Commonly excluded unless a specific insured event caused the damage |
| Cash, deeds and perishables | Often excluded |
| Jewellery, mobiles and fine art | May have specific sub-limits or exclusions |
| Customer access | Unauthorised or non-compliant access can invalidate cover |
Exclusions cause most surprises
A rug stored in Kensington may suffer from damp or mildew without a single dramatic flood event. A policy can exclude that gradual deterioration even though the item was perfectly sound at uplift. A household storing a piano may also find that cosmetic damage, mechanical failure or an internal defect isn’t covered, because the instrument was in a locked unit rather than exposed to an insured peril.
Vermin, wear and tear, scratching, denting and general breakage can be excluded unless an insured peril caused the damage, and appliance failure is another common gap. A fridge that stops working in storage hasn’t necessarily suffered an insured loss.
High-value goods need evidence
Cash, deeds, documents, perishables, plants and hazardous materials are often outside the policy altogether. Jewellery, mobile phones, money and data loss may carry hard sub-limits, and a headline sum insured doesn’t mean every item can be claimed up to that amount.
High-value goods should be declared in writing before uplift, with receipts, photographs and valuation evidence kept safely. Pairs and sets clauses can also restrict payment when one chair, one speaker or one part of a matching collection is damaged. The customer may receive the cost of the affected item, not the cost of replacing the complete set.
Storage operators may also require the unit to remain sealed and undisturbed, and the cover can be invalid where the customer doesn’t have direct access recorded. The storage contract should state who may open the unit and how every access event is logged. Information on secure self storage solutions can help a customer understand the relationship between access controls, fire protection, alarms and CCTV, and how those measures sit alongside the insurance conditions rather than replacing them.
Valuation methods and the underinsurance trap
The valuation basis determines what a successful claim can produce. Three approaches appear frequently in removals and storage arrangements, but the labels can conceal very different outcomes.
| Method | What you get | Premium impact |
|---|---|---|
| Declared value | Payment based on the sum nominated for the goods | Usually reflects the declared amount |
| New-for-old | Replacement at current retail cost, subject to conditions | Can be higher for valuable contents |
| Actual cash value | Replacement value reduced for age and wear | Depends on the declared risk |
Every policy sets its own excess, per-article cap and premium, so these figures always need to come from the individual quotation and schedule rather than a general rule of thumb. An excess is deducted from an otherwise valid settlement. It doesn’t increase a per-article limit, and it doesn’t repair an inaccurate inventory.
Declared value is not a guess
A customer who declares an item at a value above the policy’s per-article cap hasn’t created cover to that higher amount; the policy may still restrict payment to the cap, before any excess or average-clause calculation. UK storage wording also makes clear that an insurer pays only up to the value declared by the customer, so under-declaring contents creates a gap between the actual value and the insured amount.
Many storage and household policies also apply an average clause: broadly, if the total declared value falls well below the true value of everything stored, a claim can be reduced proportionally rather than paid in full. The exact threshold and calculation vary between insurers, so the policy wording should always be checked rather than assumed.
Choosing the valuation basis
New-for-old can suit ordinary furniture when the policy permits replacement with equivalent goods. Actual cash value can leave an older sofa, television or desk worth much less than its original purchase price. Declared value gives control, but only if the inventory is accurate and individual limits are identified.
A flat inventory should be built room by room, not rounded down to make a premium appear cheaper. It should list brand, model, age, condition and replacement cost, with jewellery, art, instruments, antiques, electronics and business equipment identified separately. Receipts and valuations should be attached before uplift, while the policy can still be amended.
Arranging cover through a removals company or third-party storage
The process starts with a home or video survey. In Camden or Southwark, the surveyor records volumes, access restrictions, lift arrangements, parking requirements and the condition of notable items. Those details help establish the inventory and identify goods that need separate valuation or specialist handling.
The quotation should show cover as distinct lines. Goods-in-transit protection applies to the vehicle journey, while long-term storage cover is normally separate. The customer should ask for the storage operator’s name and the full postal address of the premises, whether the facility is operated directly or through a partner.
Confirm each handover in writing
A useful custody record follows the goods through four points:
Uplift. The removals crew signs the goods-in-transit note when items are accepted at the original address.
Warehouse receipt. Storage cover starts when goods enter the designated storage arrangement, subject to the wording.
Container release. The storage operator records the seal being broken and the contents released for delivery.
Redelivery. Transit cover applies again if the policy treats the journey as a new transport phase.
That sequence can vary by policy. Some storage arrangements exclude loading, unloading or transit altogether, while others only cover goods once placed inside the unit. The customer needs the actual schedule, not a verbal summary.
Keeping the paperwork together
The customer should retain the survey sheet, inventory, insurance schedule, full policy wording, storage contract, condition report, photographs and access log. This matters particularly when a single move involves a collection address, a remote warehouse and a later delivery. Our storage units in London and storage unit West London pages set out where storage sits within the wider move.
If a storage premium feels high, two independent steps are sensible. First, ask an insurer or broker for equivalent storage cover, then compare the perils, exclusions, limits, facility address requirement and excess against the operator’s policy. Second, give the storage provider proof of that alternative policy and get written confirmation that it satisfies the rental agreement before move-in.
How storage insurance claims actually work
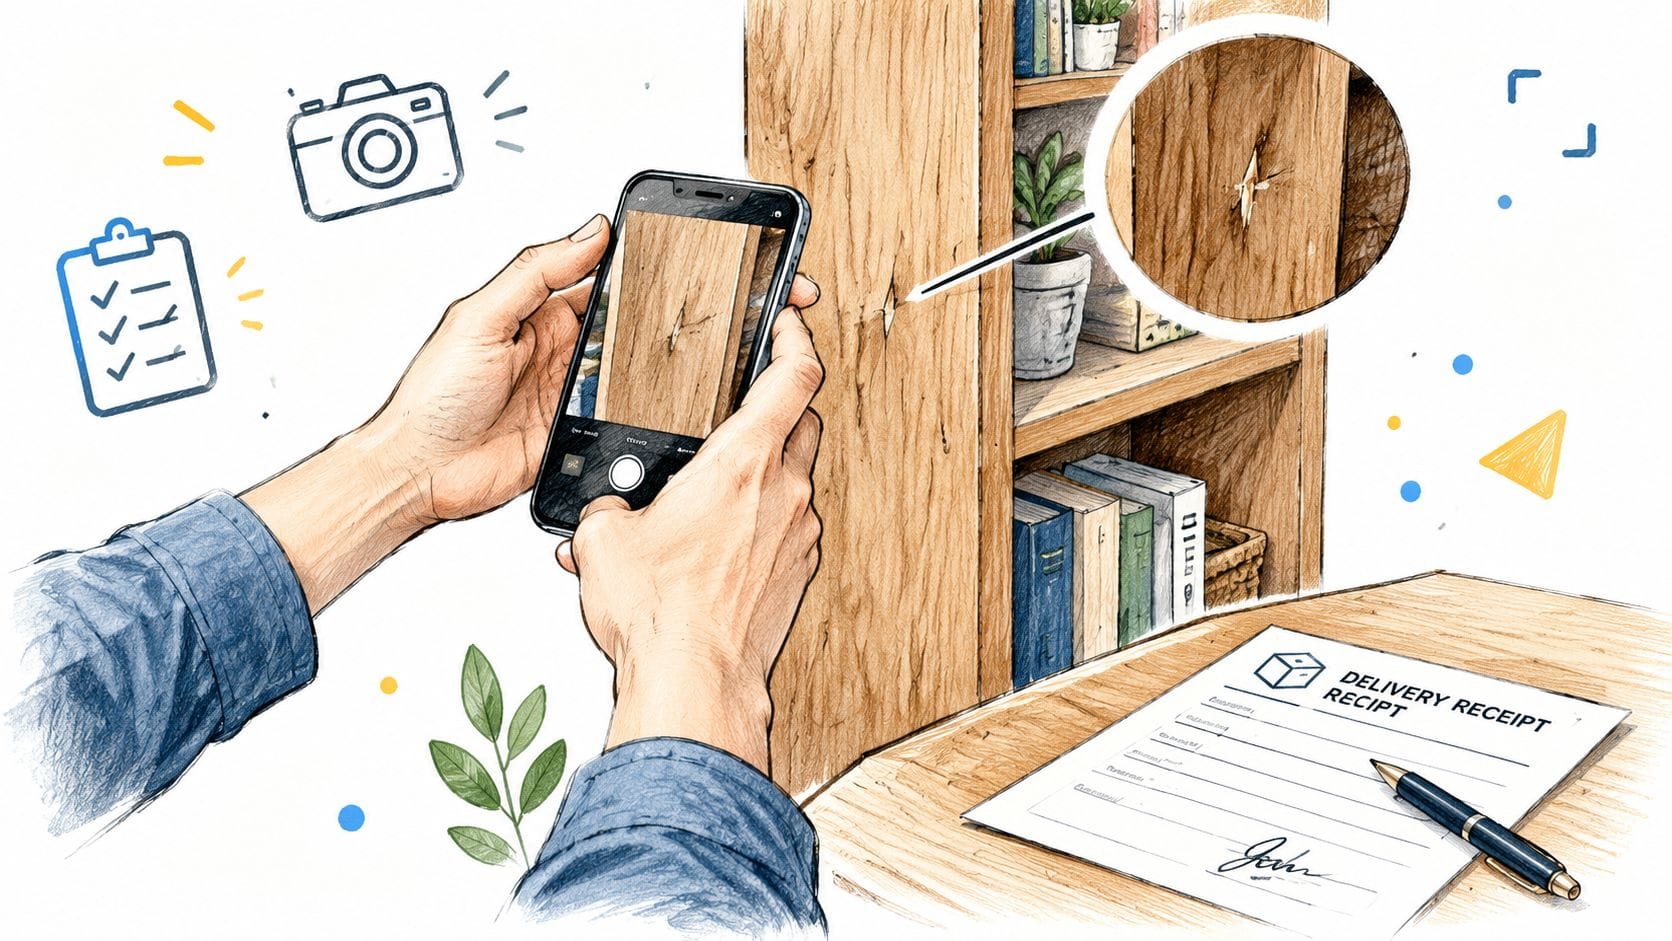
Damage should be recorded as soon as it’s noticed. At redelivery, the customer should note the issue on the delivery receipt before the crew leaves, photograph the item in place and photograph the packaging, labels and surrounding area. Most policies set a notification deadline, so the schedule should be checked immediately rather than relying on a casual phone call.
A written claim should include the survey sheet, insurance schedule, policy wording, inventory, original receipt or valuation and clear photographs. The customer should describe when the item was last seen undamaged and whether the damage was noticed during unloading, after unpacking or once the storage container had been opened.
The insurer tests the evidence
The insurer may appoint a loss adjuster to inspect the item at the customer’s address. The adjuster’s report can consider the condition before uplift, the packaging used, the likely cause, the custody phase, the declared value, the per-article limit and any average clause.
The settlement offer should be checked against the correct policy. Damage found during the vehicle journey may belong with the removals insurer, while water damage discovered in the storage unit may belong with the storage insurer. Sending the claim to the wrong party can delay the process.
Common reasons for refusal
A refusal doesn’t always mean the goods weren’t valuable. It can mean the loss falls outside the insured peril or a policy condition wasn’t met.
Late notification. The customer missed the policy’s reporting deadline.
Poor customer packing. Goods were packed into the customer’s own boxes without meeting the required packing standard.
Prohibited goods. The claim concerns jewellery, cash, deeds, perishables, plants, hazardous materials or another excluded category.
Wear and tear. The damage reflects age, gradual deterioration, mould, mildew, pests or mechanical failure.
Access breach. An unauthorised person opened or interfered with a unit that had to remain sealed.
Settlement timing depends on claim complexity and outstanding evidence rather than a fixed period, so it’s worth asking the insurer directly what to expect. If a dispute remains unresolved after the insurer’s own complaints procedure, the customer can consider the Financial Ombudsman Service where the policy and eligibility rules allow.
Practical checklist for London homeowners and renters
The right question isn’t whether storage insurance coverage exists. It’s whether the cover follows the goods without an unexplained break between uplift, warehouse storage, internal transfer and final delivery.
Before signing, the customer should obtain the full certificate and policy wording. Phrases such as “fully insured” don’t identify the valuation basis, perils or exclusions on their own.
Contract questions that need written answers
Custody transfer. When does responsibility pass from the removals company to the storage operator?
Handling periods. Are loading, unloading, internal transfers and customer-arranged transit covered?
Storage identity. Is the storage at the operator’s premises or a remote site, and does the policy name the facility and full postal address?
Valuation basis. Does the policy pay repair cost, replacement value, new-for-old or depreciated cash value?
Limits and excesses. What is the declared value, per-article limit, claim excess and any average-clause threshold?
Excluded contents. Are jewellery, cash, documents, antiques, electronics, plants, perishables and hazardous items excluded or restricted?
Damage causes. How does the policy treat damp, vermin, mould, mildew, poor packing, scratching, mechanical failure and gradual deterioration?
London buildings add practical complications. A facility serving goods from Ealing, Ruislip or Hayes may differ from one used for a move from a flood-sensitive or heavily built-up location, so it’s worth asking about fire protection, flood-risk controls, intruder alarms, CCTV, access permissions and emergency procedures. A storage unit should also have clear rules for staff visits, customer access and recorded entry.
Evidence protects the claim
Photographs should show high-value goods before packing, including serial numbers, existing marks and condition. Receipts, valuations and a room-by-room inventory should be kept in a separate digital folder, with a copy available to the insurer and storage operator.
It’s also worth recording notification periods, evidence requirements, complaint stages and whether the Financial Ombudsman Service or another insurance ombudsman arrangement applies. Renters, homeowners, landlords and businesses all face the same core issue: the goods can move between policies faster than the paperwork does.
We can arrange surveyed removals, goods-in-transit cover and assistance with secure storage, documenting the move from collection through delivery. To discuss a London move with storage requirements, contact Best London Removals Ltd for a written quotation that sets out the relevant custody and insurance stages.
This guide is intended as general information. It is not insurance advice. For advice specific to your circumstances, contact a qualified professional.